
Controversial: the biggest day trading swings in commodities often come from inventory surprises, not the headlines everyone watches.
Inventory reports force markets to reprice supply and demand in seconds. A larger than expected draw can send prices higher, and a big build usually pressures them lower.
My thesis: trade the delta between the report and the consensus. Mark your levels, write scenarios for both outcomes, and define what invalidates your idea before the release.
Keep size small and stops tight, because these releases are catalysts, not guarantees.
How Traders Use Inventory Data to Anticipate Commodity Price Reactions
Commodity inventory reports are scheduled trading catalysts. They shift supply and demand expectations fast, and they create immediate price volatility. When a report shows inventories dropping more than expected, markets reprice higher. Tightness becomes the story. When stocks build bigger than forecast, prices usually fall. Oversupply or weak demand takes over the narrative.
The gap between actual inventory and consensus matters most. That’s where the reaction lives. It works like any economic release that beats or misses. The number itself is just data. The surprise is the trade.
Expectations and positioning often outweigh the raw figure. A bullish inventory print can still trigger a selloff if traders were betting on a much larger draw and decide to lock in profits. A bearish build might spark short covering if too many people were positioned short going into the number. The catalyst isn’t the absolute level. It’s the delta between what the market priced in and what actually showed up.
Liquidity dries up around these releases. Participation disappears right before the headline, then again right after. Prices spike fast, reverse faster. The pattern is predictable: algorithms chew through the surprise in seconds, then discretionary traders step in and decide if the move makes sense or if it’s just a positioning flush. That two-stage response creates openings for traders who built a hypothesis ahead of time and waited for the catalyst to prove them right or wrong.
Core Types of Commodity Inventory Reports Traders Monitor
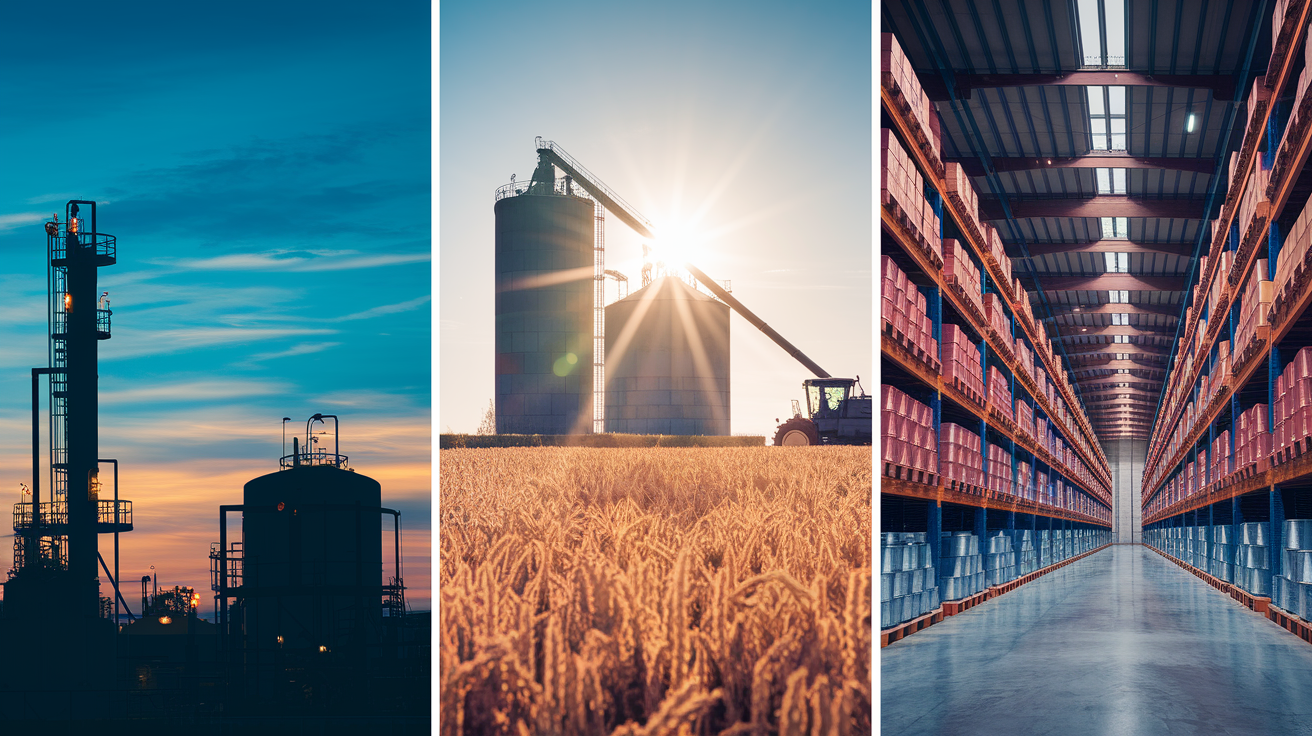
Commodity inventory reports break down into three buckets: energy, agriculture, and metals. Each has its own release schedule, seasonal quirks, and market impact. Knowing which reports move which futures and when they drop lets you build a calendar of predictable events. You can structure positions and risk management around that cadence.
Energy Inventories
The U.S. Energy Information Administration drops weekly petroleum status reports every Wednesday at 10:30 a.m. Eastern. Crude oil stockpiles, refinery utilization, gasoline inventories, distillate stocks. The Department of Energy adds data on strategic reserves. Traders care most about crude oil inventories at Cushing, Oklahoma. That’s the delivery point for WTI futures. Changes there hit the front month contract directly.
A surprise drawdown at Cushing can flip the curve into backwardation overnight. That signals tight near term supply. Refinery utilization adds color. High utilization paired with falling crude stocks means strong demand. Low utilization with rising stocks screams oversupply or weak consumption.
Agricultural Stocks
The USDA puts out quarterly grain stocks reports. Corn, soybeans, wheat, other major crops. These are deeply seasonal. The biggest market movers come around harvest and planting cycles. Weather makes agricultural inventory data extra volatile. An unexpected stock build after a drought scare can hammer grain futures. Lower than expected stocks during peak demand can produce limit up moves.
Traders also watch USDA export inspections and crush reports. Those gauge demand side inventory flows that don’t show up immediately in the quarterly numbers.
Metals and Warehousing
The London Metal Exchange and COMEX publish daily warehouse stock data. Copper, aluminum, zinc, other industrial metals. Physical delivery markets mean warehouse inventory withdrawals signal real consumption, not just paper speculation. When LME copper stocks fall hard, traders read it as tightening availability for manufacturers. Spot premiums climb, the forward curve flips into backwardation.
COMEX gold and silver inventories matter too. Eligible versus registered stock distinctions give clues about physical demand and delivery risk during contract expiry.
| Report Type | Frequency | Primary Markets Affected |
|---|---|---|
| EIA Petroleum Status (crude, gasoline, distillates) | Weekly (Wednesdays 10:30 ET) | WTI crude, Brent, RBOB gasoline, heating oil futures |
| USDA Grain Stocks (corn, soybeans, wheat) | Quarterly (March, June, September, January) | CBOT corn, soybeans, wheat futures |
| LME/COMEX Metals Warehouse Stocks | Daily | Copper, aluminum, zinc, gold, silver futures |
| Natural Gas Storage (EIA) | Weekly (Thursdays 10:30 ET) | NYMEX natural gas futures |
Identifying Bullish and Bearish Catalysts Within Inventory Trends
Compare current inventory to the five year average. That’s your baseline for directional bias. When crude stocks sit 10% above the five year average, the market prices in oversupply. Any further build reinforces the bearish view. A surprise draw starts to chip away at it. When inventories run below the five year average, you’ve got a bullish setup. Even modest draws can accelerate momentum because traders start anticipating tightness.
Historical context is everything. Absolute inventory numbers don’t mean much without knowing if the current level is normal, abnormal, or sitting at a seasonal extreme.
Thresholds like “days of supply” and working inventory capacity act as accelerators. If gasoline inventories drop below 25 days of supply during summer driving season, traders know refiners have no cushion. Any disruption spikes prices. When Cushing crude storage approaches max capacity, the market prices in forced selling or shut in production. Sharp downside follows. These aren’t random lines. They’re points where physical market participants have to change behavior. That translates straight into futures volatility.
Signals worth watching:
Large drawdown versus consensus. Market expects a 2 million barrel crude draw, actual number is 6 million. The surprise triggers instant repricing higher. Momentum follows.
Builds above seasonal norms. A 4 million barrel gasoline build in late spring, when inventories typically decline before driving season. That’s weak demand. Bearish positioning.
Inventories falling below working capacity. When stocks drop so low that logistics break down (pipelines can’t deliver efficiently, refineries adjust runs), physical premiums spike. Futures follow.
Cushing Oklahoma storage changes. It’s the WTI delivery point. Sharp draws or builds there hit front month pricing and curve structure hard. Contango versus backwardation shifts fast.
Seasonal highs or lows creating abnormal spreads. Inventories at multi year lows in winter (heating oil) or summer (gasoline) compress calendar spreads. Carry trade opportunities open up.
Inventories at multi year extremes. When stocks hit five or ten year highs or lows, the market reprices tail risk. Either scarcity premiums or oversupply discounts. Volatility around the next reports amplifies.
Real Market Examples of Inventory Reports Acting as Trading Catalysts
Early 2023, a Wednesday morning. The EIA reported a 9.2 million barrel crude oil inventory draw. Consensus was 1.5 million. WTI futures spiked $3 per barrel within 90 seconds. The front month gapped through technical resistance at $78, briefly touched $81, then consolidated. The outsized draw came from refinery runs above 95% utilization plus strong exports. Demand was absorbing supply faster than the market had priced.
Traders positioned long ahead of the release with a tightening thesis saw immediate validation. Shorts scrambled to cover. That amplified the move. The catalyst wasn’t just the draw. It was the surprise size relative to expectations and confirmation that refinery demand stayed strong.
Mid 2021, metals. A series of sharp LME copper warehouse stock withdrawals triggered momentum buying. Copper futures climbed from $4.20 per pound to nearly $4.90 within three weeks. The inventory decline matched up with production disruptions in Chile and strong Chinese manufacturing data. Structural tightness became the narrative. Each daily warehouse report showing more withdrawals acted as a fresh catalyst. Momentum buyers stayed engaged. Underweight funds had to chase.
The sequence showed how serial inventory catalysts (daily updates versus a single weekly release) can sustain directional moves longer. Each new data point either reinforces or challenges the thesis.
Agriculture got dramatic in March 2022. The USDA grain stocks report revealed corn inventories 12% below analyst estimates. Corn futures opened limit up the next morning. May contracts jumped 50 cents per bushel before trading resumed. The shock reflected stronger than expected ethanol demand, reduced harvested acreage from drought, and export demand that private forecasters had missed.
Farmers holding cash grain saw immediate basis strengthening. Commercial hedgers scrambled to cover short futures. That feedback loop kept prices elevated for weeks. The catalyst worked because it revealed a structural supply shortfall that couldn’t be fixed quickly. Planting season was months away. Inventories had no immediate source of replenishment.
The typical price discovery sequence after a surprise inventory release:
Initial algorithmic spike or drop within seconds. HFT systems parse the headline and compare it to consensus. First 60 to 80% of the move happens with minimal human involvement.
Human discretionary evaluation over the next 5 to 15 minutes. Traders assess whether the surprise aligns with other fundamental data (demand indicators, production reports, export flows) and whether positioning was crowded wrong.
Follow through or reversal in the 30 to 60 minute window. Larger institutional players decide whether to reinforce the move or fade it. Usually based on technical levels and risk reward at the new price.
Sustained trend or mean reversion over the rest of the session and following days. Determined by whether subsequent data and price action keep validating the initial catalyst or reveal it as a one off anomaly.
Trading Strategies for Acting on Inventory Report Catalysts
Traders split their approach: pre report versus post report positioning. Pre report means building a small directional bias based on recent demand indicators, weather patterns, or refinery activity, then waiting for the catalyst to validate the thesis. If crude inventories have been drawing for three straight weeks and refinery utilization stays high, you might go long WTI the day before the EIA report. Tight stop below recent support. You’re betting on another draw.
Risk is defined. Catalyst is scheduled. The trade either works fast or gets stopped with minimal damage. Post report positioning waits for the initial volatility spike to calm down, then trades the follow through or mean reversion based on whether the reaction looks justified or overdone.
Breakout and momentum strategies work when inventory surprises align with existing fundamental trends. Natural gas storage shows a larger than expected injection during shoulder season (spring or fall). That confirms weak demand. A breakout below prior support becomes high probability because the fundamental catalyst reinforces the technical setup. Momentum traders layer in as the move extends. Trailing stops capture follow through while protecting against sudden reversals.
The trick is confirming that the inventory data shifts the supply demand narrative enough to sustain directional pressure beyond the first spike.
Spread trading offers lower volatility exposure to inventory driven moves. You capture relative value between related commodities or contract months. The crack spread (crude versus gasoline and distillate) widens when refinery margins improve. Often triggered by gasoline inventory draws or crude builds. If the EIA reports tight gasoline stocks and ample crude supply, the crack spread tightens the relationship between input cost and output value. That’s a trade without taking outright directional risk in crude or gasoline alone.
Calendar spreads in the same commodity react to inventory levels too. Low stocks create backwardation. High stocks create contango. You can position for curve shape changes rather than flat price moves.
Practical strategies around inventory catalysts:
Fade the spike. If the initial reaction looks excessive (a $4 crude rally on a 3 million barrel draw when fundamentals are mixed), wait 20 to 30 minutes for things to settle. Then fade the move back toward pre release levels. Bet on profit taking and mean reversion.
Breakout continuation. When an inventory report pushes price through a clear technical level (resistance on a bullish draw, support on a bearish build) and volume confirms, enter in the direction of the break. Stop just inside the broken level.
Seasonal pattern trades. Use historical inventory patterns (heating oil draws in winter, gasoline draws before summer) to position ahead of expected seasonal tightness. Let the weekly reports act as serial catalysts to carry the trade.
Correlation based hedging. If crude inventories suggest tightness but you’re worried about broader risk off sentiment, hedge a long crude position with short equity index futures or long VIX exposure. Isolate the commodity specific catalyst from macro risk.
Options based volatility plays. Buy short dated straddles or strangles ahead of high impact inventory releases (EIA crude, USDA grains) when implied volatility is cheap relative to the expected move. Profit from the spike in realized volatility regardless of direction.
Managing Volatility, Liquidity, and Risk Around Inventory Releases
Liquidity thins in the minutes before major inventory releases. Then it evaporates during the headline print. Even modest order flow produces wild price swings. Market makers widen bid ask spreads to protect themselves from getting run over by the initial algo driven reaction. Stop orders cluster just above resistance or below support, ready to trigger cascading moves.
Traders who try to position large size in the 60 seconds after a release usually suffer slippage. What looks like a 50 tick favorable move on the chart might only yield 30 ticks of actual fill quality after accounting for spread widening and partial fills at worse prices. High frequency systems dominate the first wave. Human traders do better waiting for the second wave when liquidity returns and the market digests whether the initial spike made sense.
Position sizing and stop placement keep you from getting whipsawed by false breakouts. Those happen constantly in the 5 to 10 minutes after inventory data. Size positions to withstand a 1.5x to 2x average true range move against the trade without hitting a stop that’s too tight. Keep total risk per trade under 1 to 2% of account equity.
If average daily range in crude is $2 and an inventory release typically produces a $3 intraday swing, a stop placed $1.50 away from entry gives the trade room to breathe through initial noise. You’re not risking catastrophic loss if the thesis is wrong. Scaling in after the initial spike works too. Enter 50% of intended size immediately, add the remaining 50% on a pullback. That reduces average entry cost and lets you confirm follow through before committing full capital.
The goal is participating in real catalyst driven moves while avoiding the random liquidity gaps that plague the first 120 seconds of any major data release.
Final Words
in the action we showed how surprise drawdowns or builds versus consensus shift supply-demand expectations and spark sharp price moves. We covered the main reports—energy, ag, metals—and how to read bullish and bearish signals against the five-year average.
Then we ran real examples and practical setups: pre- versus post-release positioning, breakout or fade choices, and spread plays. Risk rules matter more here. Size small, use firm stops, expect slippage when liquidity dries up.
Use this framework when using commodity inventory reports as trading catalysts, keep the plan simple, and stay disciplined — that’s the edge.
FAQ
Q: What is the 3 5 7 rule in trading?
A: The 3 5 7 rule in trading is a simple scaling and target framework: set short-, medium-, and longer-term targets or stops at 3, 5, and 7 units (ticks/points/days) to size and time trades.
Q: What are the 7 C’s of commodities?
A: The 7 C’s of commodities are consumption, competing crops, cost of production, currency, carry (storage), country risk, and climate—seven supply-demand factors traders watch to judge catalysts and price risk.
Q: What is the 90% rule in trading?
A: The 90% rule in trading is a discipline that says cut a position when it reaches about 90% of your predefined loss limit, preserving capital and avoiding larger drawdowns.
Q: What is the 7% rule in stock trading?
A: The 7% rule in stock trading commonly limits individual position loss or avoids entries after roughly a 7% gap, helping control risk and preventing chasing volatile moves.