
Think earnings are the only time stocks move? Think again.
8-K filings are the SEC’s unscheduled alerts that often move prices before analysts catch on.
This post shows how to read 8-Ks to spot stock-moving catalysts, which item codes to watch, how to scan fast, and what proves the thesis wrong.
You’ll cut research time, catch surprises before the market does, and build clear trade-ready theses with levels and invalidation.
Key 8-K Sections That Reveal Upcoming Corporate Catalysts
Form 8-K is the SEC’s “current report” that public companies use to announce unscheduled material events between their quarterly and annual filings. Unlike the predictable rhythm of 10-Qs and 10-Ks, an 8-K drops when something important happens. Often before the market’s fully priced it in. Investors watch these filings because they offer a direct, unfiltered view of changes that can shift a company’s trajectory. Whether that’s a new partnership, a leadership shakeup, or an early look at financial performance.
8-K disclosures frequently trigger measurable stock reactions because they arrive outside normal earnings cycles and catch the market off guard. A surprise CEO departure filed on a Tuesday afternoon can move shares before the opening bell Wednesday. A material agreement disclosure might reveal a customer win that changes revenue forecasts for the next two quarters. Unlike press releases, which companies control and spin, 8-Ks follow strict SEC format and timing rules. That makes them a cleaner source for spotting real catalysts before broader consensus forms.
Understanding which specific items tend to carry weight saves hours of sifting through administrative noise. Certain disclosures consistently correlate with price volatility. Knowing their item codes lets you zero in on what matters. Learning to read the high-impact sections quickly shortens your research loop and puts you ahead of investors who wait for analysts to summarize the news days later.
Item 1.01 (Entry into a Material Definitive Agreement): Signals new contracts, partnerships, or financing deals that can materially change revenue or capital structure. Often moves stock if the counterparty or deal size is significant.
Item 1.03 (Bankruptcy or Receivership): Discloses insolvency proceedings. Immediate red flag that typically drives sharp downside moves and halts trading in some cases.
Item 2.02 (Results of Operations and Financial Condition): Contains preliminary earnings, pre-announcements, or updates outside the normal calendar. Can create instant repricing if numbers deviate from consensus.
Item 2.05 (Costs Associated with Exit or Disposal Activities): Reveals layoffs, plant closures, or restructuring charges. Useful for spotting operational stress or strategic pivots before they show up in quarterly results.
Item 5.02 (Departure of Directors or Certain Officers; Election of Directors; Appointment of Certain Officers; Compensatory Arrangements): Flags C-suite changes, resignations, or new hires. Especially impactful when it involves the CEO or CFO, as leadership transitions reset market expectations.
Item 8.01 (Other Events): Catch-all for anything material that doesn’t fit neatly elsewhere. Regulatory approvals, product launches, legal settlements, FDA decisions. Often contains hidden catalysts because it’s less standardized and requires closer reading.
How to Systematically Analyze an 8-K Filing
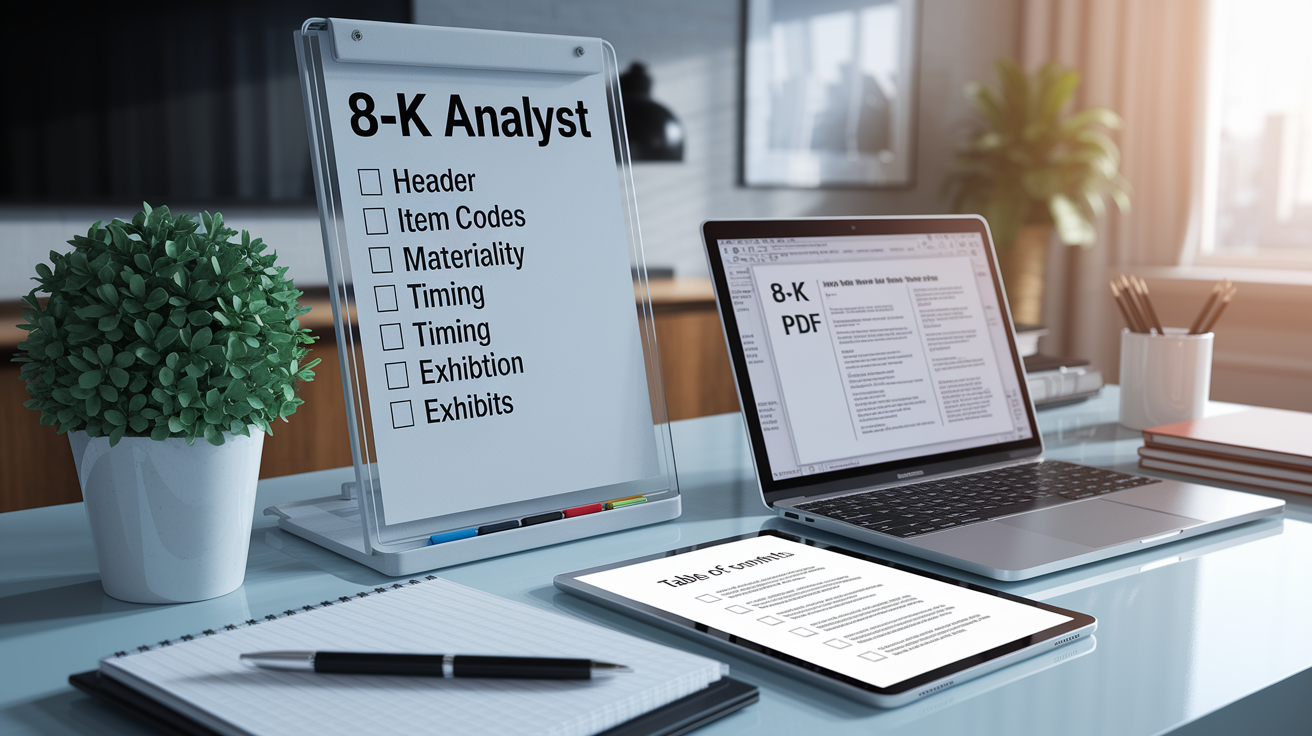
Reading an 8-K efficiently starts with the header and item code. Pull the filing from EDGAR, note the date and time it hit the wire, then scan the table of contents or opening paragraph to identify which items the company checked. Flag any item from the high-impact list and prioritize those sections first. If the filing cites multiple items, the combination often tells a bigger story. For example, Item 1.01 plus Item 9.01 (exhibits) usually means a definitive agreement is attached, and the dollar amounts live in the exhibit.
Next, compare the new disclosure against the company’s most recent 10-Q or 10-K and any prior 8-Ks from the last six months. Ask whether this event was telegraphed in prior guidance, mentioned in risk factors, or comes as a complete surprise. Cross-check announced deal terms, executive changes, or financial updates with what management said on the last earnings call. Material deviations are the events that move stock. Like a CEO stepping down two months after reaffirming commitment, or a customer contract disclosed weeks after management downplayed pipeline risk.
Assess materiality by looking for explicit numbers. Contract values, consideration paid, debt amounts, employee counts, dates, and deadlines. If the 8-K includes phrases like “effective immediately,” “termination,” “default,” “restatement,” or “failure to satisfy,” treat it as high-priority. Soft language or missing dollar figures often indicate routine administrative updates that won’t move the needle.
Scan the tone and level of detail. A terse, formulaic disclosure with no context usually means the company is meeting minimum legal requirements and doesn’t want to elaborate. Unusually detailed narrative or multiple exhibits can signal the company expects market questions and is getting ahead of them. Both extremes matter. Terseness can hide problems, while over-explanation sometimes reveals management anxiety.
To save time, build a template that captures filing date, item codes, counterparties, dollar amounts, effective dates, and your one-sentence thesis on potential impact. Run through that template in five minutes, and you’ll know whether the filing warrants deeper research or can be filed under “noise.”
Interpreting High-Impact Items in Detail
Material agreements disclosed under Item 1.01 often reshape near-term expectations because they lock in revenue, financing, or operational commitments that weren’t modeled by the street. A new supply contract worth 15 percent of annual revenue changes things. A credit facility that extends runway by two years changes things. A partnership granting exclusive distribution rights changes things. The market reprices based on the disclosed economics, payment terms, milestones, earnout structures, and whether the agreement includes performance guarantees or cancellation clauses. If the counterparty is a household name or a Fortune 500 customer, the credibility boost alone can lift the multiple. Conversely, agreements with unusual contingencies or material adverse change provisions can introduce new risk that wasn’t in the model.
Early financial figures filed under Item 2.02 frequently serve as a preview of formal earnings and can trigger significant premarket or after-hours moves. When a company files preliminary results or updates guidance between quarters, it’s often because the numbers are materially different from what the market expects. Either much better or much worse. These filings sometimes include limited commentary, so you parse revenue growth rates, margin direction, and any mention of one-time items to estimate the full quarter’s picture. If management files an Item 2.02 two weeks before the scheduled earnings date, it’s usually to control the narrative around a surprise. The stock will price in that surprise immediately. The absence of detail can be as telling as the numbers themselves. Vague language about “challenging conditions” without quantification often precedes a larger disappointment.
Governance and regulatory events carry weight because they alter the company’s operational credibility and risk profile. C-suite departures, auditor changes, delisting notices, FDA approvals. An unexpected CFO resignation raises questions about financial controls and reporting quality, often compressing valuation multiples until a credible replacement is named. Auditor resignations, especially if accompanied by disagreements disclosed under Item 4.01, can freeze institutional interest and trigger covenant reviews by lenders. On the positive side, a disclosed regulatory approval or removal of a going-concern opinion can unlock value by eliminating binary risk that was holding back buyers. These events don’t always show up directly in next quarter’s numbers, but they reset the market’s confidence in management’s ability to execute and report accurately.
Practical Examples of 8-K Catalysts Affecting Stock Prices
Consider a mid-cap software company that filed an Item 5.02 on a Thursday after market close, disclosing the immediate resignation of its CEO “to pursue other opportunities,” with the CFO named interim CEO. The filing included no explanation beyond the standard boilerplate, no severance details, and no commentary on strategic direction. Shares opened down 8 percent the next morning. Investors interpreted the abrupt departure and lack of detail as a red flag, especially given that the company had missed guidance the prior quarter. Within a week, the stock fell another 5 percent as sell-side analysts downgraded on “management uncertainty” and delayed their price targets pending clarity on the leadership search. The 8-K itself contained fewer than 200 words, but the absence of context and the timing created a vacuum that the market filled with negative assumptions. Mid-quarter, with no prior signal. In this scenario, Item 5.02 was the catalyst, and the lack of accompanying narrative amplified the sell-off.
In a different case, a small-cap biotech filed an Item 8.01 8-K on a Monday morning announcing that the FDA had granted Fast Track designation for its lead drug candidate. The filing included the program name, indication, and a brief statement on the expected timeline benefits. Shares jumped 22 percent intraday. Driven by the regulatory de-risking and the implication that a filing could happen sooner than the street had modeled. The 8-K was only one page, but the Item 8.01 label and the phrase “Fast Track designation” were enough to trigger algorithmic scanners and bring in momentum buyers. Within 48 hours, two analysts initiated coverage with buy ratings, citing the reduced approval risk. Here, a single-page 8-K under the catch-all “Other Events” item delivered a clear, actionable catalyst that the market priced in immediately. That’s why Item 8.01 filings require close attention despite their generic label.
Comparing Multiple 8-K Filings for Trend Insight
Tracking a company’s 8-K history over several quarters can reveal patterns that surface before they become obvious in the formal financials. Repeated Item 1.02 filings showing contract terminations, or multiple Item 2.03 disclosures around amendments to credit agreements, often signal deteriorating business conditions or tightening liquidity that hasn’t yet shown up in revenue declines or official guidance cuts. When a company files three separate 8-Ks in six months related to the same credit facility, that progression tells you something. First an amendment, then a waiver, then an acceleration notice. The lenders are losing confidence and the company is burning through covenant cushions faster than management is admitting publicly.
Similarly, recurring Item 5.02 filings announcing new CFO appointments every 12 to 18 months, or a pattern of sudden director resignations, can indicate deeper governance or operational problems that aren’t being disclosed in risk factor updates. If you see the same types of events clustering in a short window, you’re often looking at a company in crisis before the market fully prices it in. Executive exits, auditor changes, restatement notices. Conversely, a series of Item 1.01 filings with progressively larger deal values and recognized brand-name counterparties can confirm an emerging competitive moat or accelerating product adoption ahead of the next earnings beat. Pattern recognition across multiple 8-Ks turns discrete events into a narrative, giving you an information edge over investors who only read the most recent filing in isolation.
Building a Simple Investor Framework for Reading 8-Ks
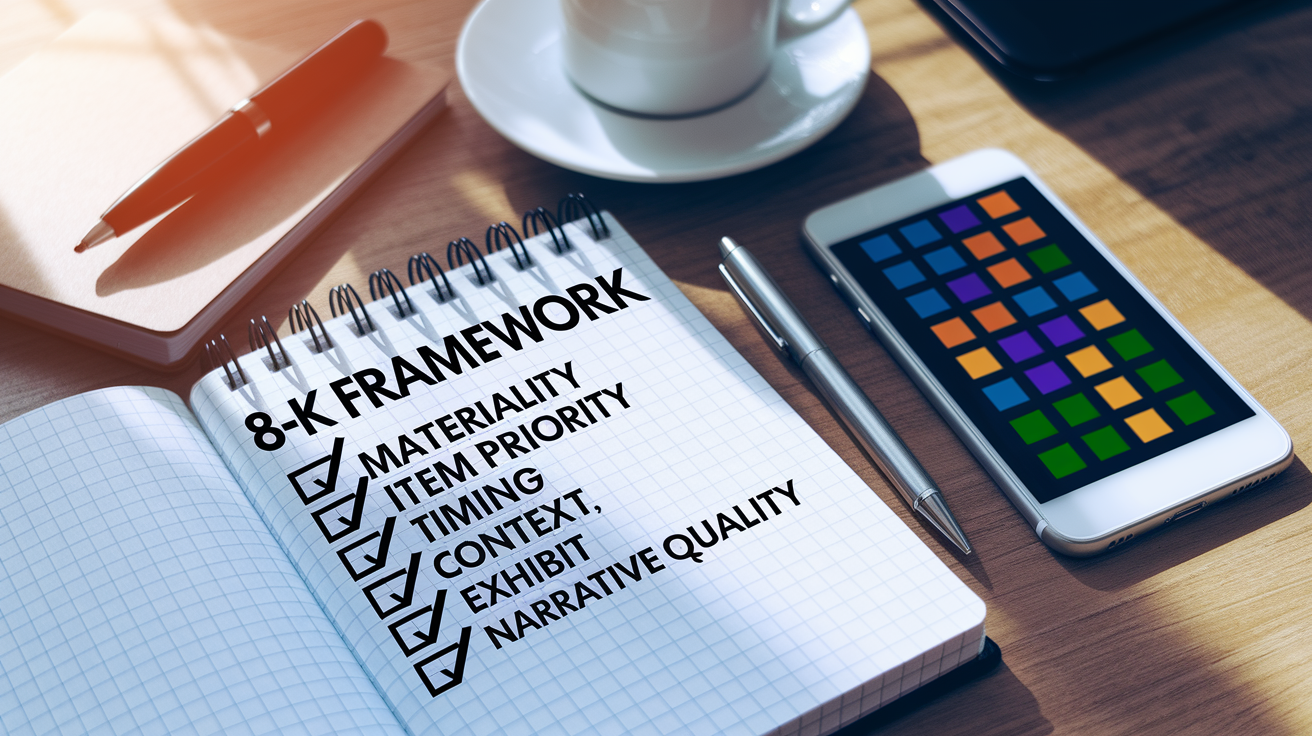
A practical evaluation framework speeds triage and reduces false signals. Start with five quick checkpoints every time a new 8-K hits your feed.
Materiality: Does the disclosure include explicit dollar amounts, percentages of revenue or assets, employee counts, or binding dates? If numbers are missing or vague, downgrade urgency.
Item priority: Is it one of the high-impact codes (1.01, 1.03, 2.02, 2.05, 5.02, 8.01) or a routine item like 5.07 (submission of matters to a vote) with no financial content?
Timing and context: Does the filing arrive outside the normal earnings calendar, immediately after a prior surprise, or in close proximity to other governance or financing events?
Deviation from baseline: How does the event compare to the company’s historical pattern? First-time occurrence, escalation of prior issues, or continuation of positive momentum?
Exhibit and narrative quality: Are definitive agreements, pro forma financials, or board resolutions attached? Is the language detailed and forward-looking, or minimal and defensive?
Apply this checklist in the first two minutes after opening the filing. If three or more boxes check positive, move the 8-K to your priority queue for deeper research, exhibit review, and comparison against your financial model. If fewer than two boxes check, file it as administrative noise and move on. This simple scoring system keeps you focused on the 8-Ks that actually matter and prevents you from spending time on routine updates that won’t change your investment thesis or position sizing.
Final Words
Price often moves the moment an 8-K hits the wire. We covered what an 8-K is, the high-impact items like material agreements, earnings updates, and governance changes, and a repeatable four-step read that saves time.
Use the checklist every time. Check filing date, flag Items 1.01, 2.02, 5.02, and 8.01, compare to prior filings, and size risk before you act.
Stick to the process. Practicing how to read 8-K for upcoming corporate catalysts will make your reactions faster and less noisy, and you’ll trade with more confidence.
FAQ
Q: How to read Form 8-K and what is a corporate 8-K?
A: A Form 8-K is a current report companies file to disclose material events. Read it by checking the date, scanning high-impact items (agreements, earnings, leadership, regulatory), and reviewing exhibits for specifics.
Q: What are 10-K and 10-Q reports, and how do you read a 10-K?
A: 10-Ks and 10-Qs are annual and quarterly reports, respectively. Read a 10-K by focusing on management discussion, audited financials, risk factors, footnotes, and trends versus prior years to spot durable changes.